Home · Costs & Insurance
What roof work costs in Burbank, and how insurance pays
How much does roof work cost in Burbank, and does insurance cover it?
Published national guides put roof repairs commonly between $400 and $1,800 depending on the detail, and full replacements priced by the square and the material class. Burbank jobs divide by exposure: wind and storm damage on a dated event is the claim-shaped work, heat and age wear on the studio-era stock is the owner's replacement arithmetic, and hillside roofs in the Verdugo fire interface carry a specification question, fire class, that flatlands quotes never meet. An inspection that separates wear from storm damage in writing is the document everything prices from. The written estimate after an in person inspection is the number that matters.
Burbank pricing starts with the exposure read. Santa Ana wind damages roofs on dates; valley heat ages them on a schedule; and the Verdugo interface prices a specification, fire class, into hillside work. Published national guides put repairs at $400 to $1,800 by the detail, tarping at $250 to $750, and replacements by the square and material class. Nobody honest quotes a firm total by phone; the number is built from an in person inspection and a written estimate, in that order.
Compiled from published national guides and local data; reviewed by the Verdugo Roofing Co research team. Last reviewed November 16, 2026.
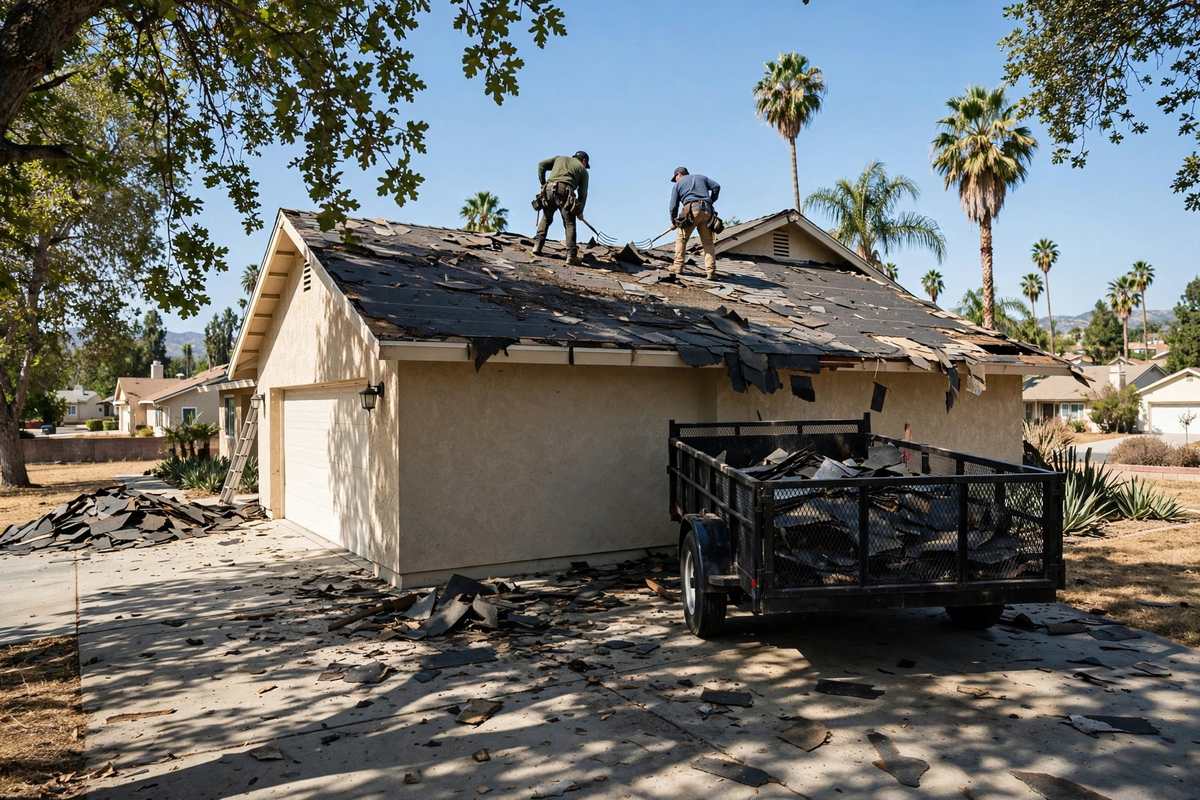
Typical cost ranges
| Job | Typical range | What moves it |
|---|---|---|
| Leak repair at a flashing or valley detail | $400 to $1,800 | Priced against the surrounding field's remaining life, stated in the scope. |
| Emergency tarping and storm documentation | $250 to $750 | Anchored for the gusts still in the forecast; dated photographs are part of the product. |
| Wind damage section repair | $900 to $3,200 | Scoped slope by slope from the exposure read and the event record. |
| Full replacement, Class A architectural shingle | Priced by the square after inspection | Deck, underlayment, ventilation, and cool-roof compliance itemised separately. |
| Full replacement, standing seam metal | Priced by the square after inspection | The hillside's long-horizon line; fire class and access stated in the quote. |
Ranges are published guide figures, not a quote for your home. Your estimate is written after an in person inspection and should name the storm findings, the wear findings, and, on hillside addresses, the fire class as separate lines.
How insurance pays for this work
The deductible question
Standard deductibles commonly run $500 to $2,500. Against these bands, the split matters more than the arithmetic: a dated wind event's damage is a claim, argued from photographs taken in its own week, while wear is never a claim and is priced as the owner's schedule. Hillside owners should ask the fire-class question of their insurer before replacement, not after, because the specification the policy rewards must be the one on the roof when the inspector comes.
Request a callback
Prefer to talk later? Leave your details and an independent local pro will call you back. No charge to you, no obligation.
Verdugo Roofing Co is a free referral service. Submitting this form connects you with independent local contractors who provide the work.